P1-HNW
Insurance-to-Value on a High-Value Home: Why Your Rebuild Estimate Drifts
Your policy limit stops tracking rebuild cost the day you set it. Learn how extended and guaranteed replacement differ and what to review.
P1-HNW
Your policy limit stops tracking rebuild cost the day you set it. Learn how extended and guaranteed replacement differ and what to review.
P1-HNW
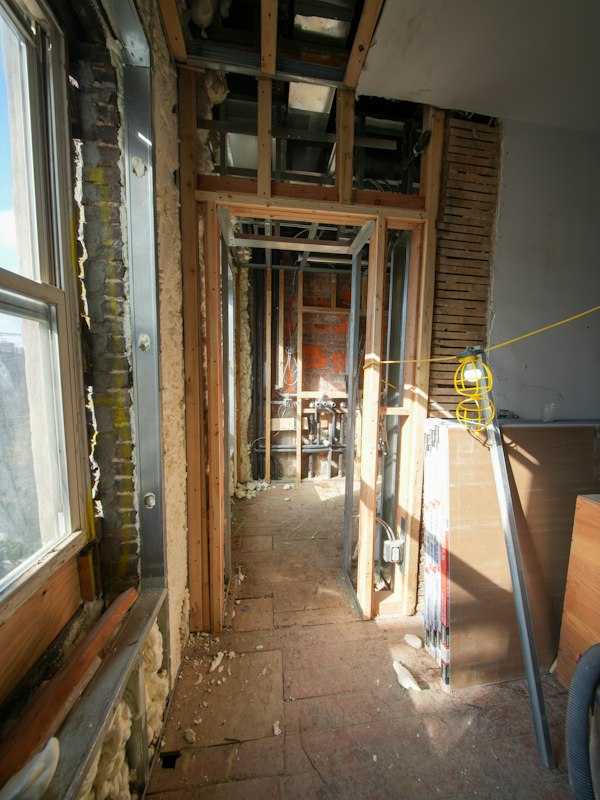
A major renovation changes the risk your policy was priced for. Here's what to tell your broker, what to require from contractors, and what to document.
P1-HNW
New York requires workers' comp for household staff at 40+ hours a week. Your homeowners policy won't cover it. Here's how to close the gap.
P1-HNW
A closed-up second house is unoccupied, not vacant, and the freeze clause has two paths. Here is what your policy expects from October to April.
P1-HNW
Multi-property owners face compounding insurance risk in 2026. Here's how to manage documentation, protective devices, and broker conversations across a high-value portfolio.
P1-HNW
Most preferred-tier policyholders never use the risk mitigation services their carrier offers. Here's what's available, where it falls short, and how to build your own risk record.
P1-HNW
High-value home policyholders aren't immune to the 2026 insurance market. Here's what preferred-tier homeowners should document and prepare before their spring renewal conversation.
P1-HNW
If you own multiple high-value homes, spring reopening is the moment coverage gaps surface. Here's what most multi-property owners don't know about vacancy provisions, documentation requirements, and protective devices.
P1-HNW
Private carriers conduct their own risk assessments — and homeowners who arrive prepared are in a fundamentally different position. Here's what to bring.