The Insurance Inspector Is Coming Thursday. Here's What They're Actually Scoring.
Insurance inspections aren't pass-fail. Here's the rubric inspectors use, the three letters you can get, and what to have ready before they arrive.
A letter arrives, or an email, or a phone call from an unfamiliar number: an inspector will visit your home on Thursday. Most homeowners treat it as a pass-fail exam with an unwritten rubric. It isn't one, and the people who handle it well are the ones who know what's on the scoresheet before the visit.
Why carriers inspect now: new policy, renewal, renovation, or a flag from the flyover
Four things usually trigger a visit. A new policy, because the insurer wants to confirm what it just agreed to cover. A renewal on an older home, where the roof or systems may have aged since the last look. A renovation or permit that changed the house. And a flag from aerial or satellite imagery, which now lets carriers spot a worn roof, a missing fence or a trampoline without anyone setting foot on your lot.
That last one surprises people. Here's what most people don't know: by the time an inspector knocks, the carrier often already has a file on your house built from imagery and public records. The visit confirms or corrects it. If the file is wrong, the visit is your chance to fix it.
None of this is adversarial. A carrier that can't see a risk can't price it, and a carrier that prices it wrong raises rates for everyone. The inspection closes an information gap, and it closes it in both directions.
Exterior, interior, four-point: what each visit covers and how long it takes
Three formats cover most visits. An exterior-only visit is a walk around the outside with photos of the roof, siding, fencing, pool and yard. It often takes 30 minutes or less. An interior visit adds the basement, attic, utility areas and the major systems, and can run a few hours on a larger home.
A four-point inspection looks at only four things: roof, electrical, plumbing and HVAC. Insurers commonly ask for one on homes roughly 20 to 30 years old or older. The report typically costs $75 to $250 and sometimes up to $450, and the visit usually takes under an hour. Your agent will tell you which format applies. Ask, because the answer changes how you prepare.
The rubric: roof, electrical panel and wiring, plumbing and water heater, heating, foundation
Inspectors score the systems that cause the largest and most frequent losses. Expect these.
- Roof: age, missing or curling shingles, moss, sagging, flashing and visible patches. Many carriers care more about remaining life than age alone.
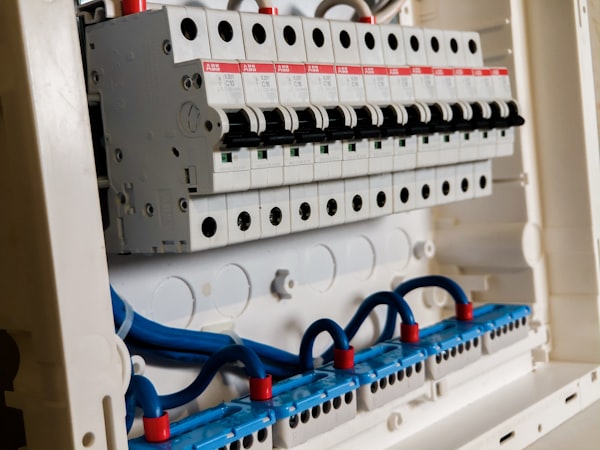
- Electrical: the panel's brand and condition, whether it has a known problem model, visible knob-and-tube or aluminum branch wiring, and open or double-tapped breakers.
- Plumbing and water heater: supply line material, active leaks, stains under sinks, and the water heater's age and drain pan.
- Heating: furnace or boiler age, service tags, and any wood stove or fireplace insert.
- Foundation and drainage: cracks, standing water, and whether the ground slopes toward the house.
Smoke detectors and carbon monoxide alarms get a look too. One more note: an inspection is rarely pass or fail. It is a record of condition, and the carrier decides what to do with it.
The liability list: pool fencing, trampolines, deck rails, walkways, the dog
Property condition is half the visit. The other half is liability, meaning the things that could injure a guest and lead to a lawsuit. Inspectors look for pools without a fence or self-latching gate, trampolines (some carriers exclude them or require a safety net), loose deck railings, cracked or lifting walkways, and missing stair handrails.
Dogs come up as well. Some carriers restrict certain breeds or ask about bite history, and a visible dog can prompt a question. If you have one, be ready to answer plainly. A surprise discovered at the inspection is harder to resolve than a fact you volunteered.
The three letters you can get afterward, and what a "cure period" actually allows
After the visit, you will usually get one of three outcomes.
No change. The file matches the house and you hear nothing. Most inspections end here.
A conditional letter. The carrier will keep your policy if you fix specific items by a deadline. That window is the cure period, and the length varies by carrier and state, so read your letter for the exact date. Cure periods are usually measured in weeks, not months. The letter should list each item and what proof closes it out, such as a receipt, a photo or a contractor's sign-off.
Nonrenewal. The carrier declines to renew at the end of the term. State law sets the notice you must receive, which is why a nonrenewal letter should never sit unopened. If you get one, call your agent the same day. An independent agent can often move the file to another carrier, and a documented fix improves your odds.
A conditional letter is an opportunity, not a verdict. The carrier is telling you exactly what it needs to keep covering you.
What to have on the counter: permits, invoices, alarm certificates, roof documentation
Put a folder on the kitchen counter before the inspector arrives. In it: the permit and invoice for any roof, electrical, plumbing or HVAC work; the roof's installation date and shingle warranty; your water heater's install date; the electrician's invoice if the panel was replaced; and your alarm monitoring certificate if you have a monitored system.
Photos help too. A dated photo of the attic decking, the water shutoff valve, or the panel with its cover off answers a question before it's asked. Inspectors work from limited time and a checklist. Evidence in hand turns "can't verify" into "verified," and that can change the letter you get.
Running your own assessment first, and why the carrier prefers it too
You can walk your own house with the rubric above. Most owners find two or three items they'd have missed, which is exactly what you want to find on Wednesday and not Thursday.
A Rafter assessment does this systematically. It uses AI to review your roof, electrical, plumbing, heating and water protection, then produces a prioritized mitigation plan that ranks fixes by claim risk and cost. It also builds a dated record of the home's condition, with the photos, invoices and maintenance dates an inspector asks for. Protective devices matter most here. A monitored alarm, a water shutoff valve and leak sensors are the items carriers most often credit, and Rafter helps you document them so the credit lands on your policy.
Carriers prefer this too. A homeowner who shows up with a verified record shortens the visit, reduces disputes and gives underwriters a file they can price with confidence. Everyone gets a better outcome.
Next step: before the inspector arrives, schedule your Rafter assessment at rafterhome.com, fix or document what it flags, and put the folder on the counter. If your visit is already on the calendar, book it now, so the findings and receipts are ready when the knock comes.